Profit vs Cash Flow: Why a Profitable Company Can Still Fail
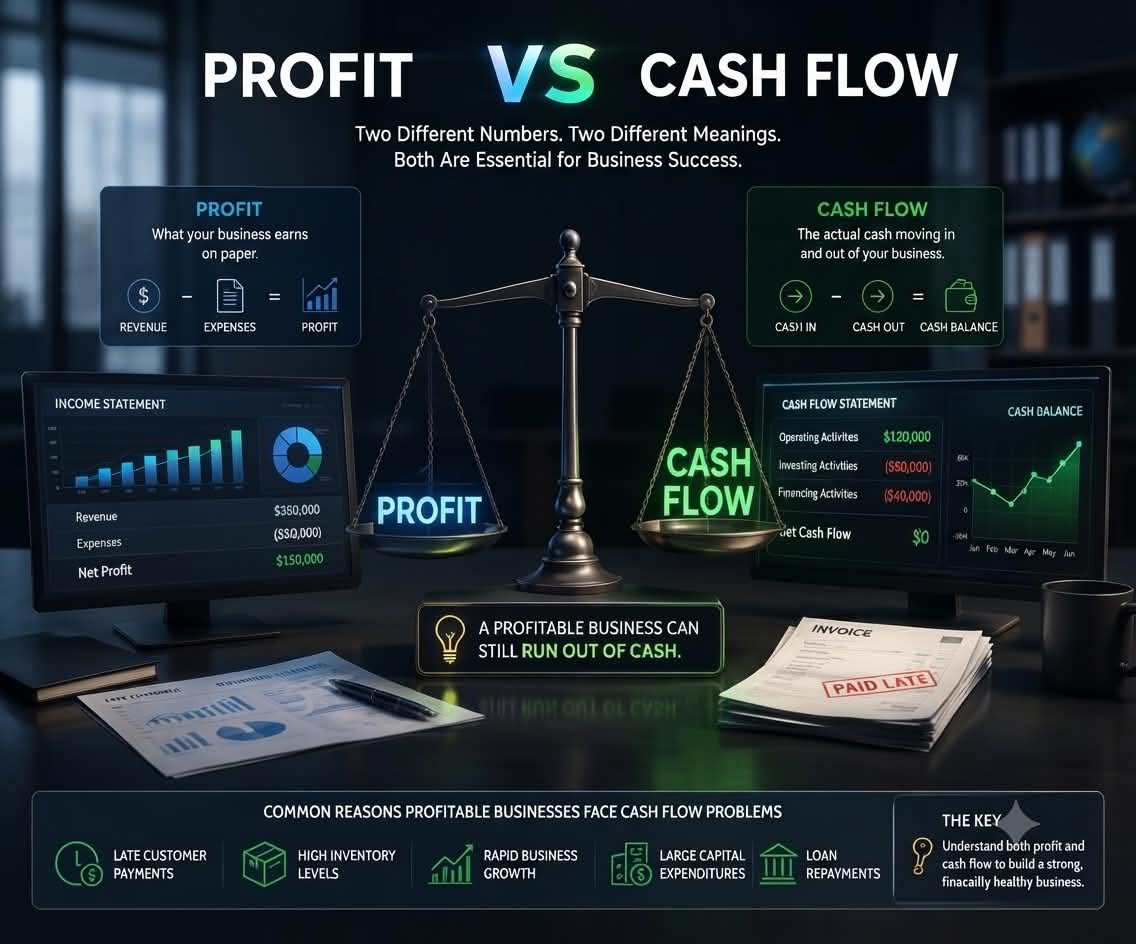
A company can report a profit and still struggle to pay its bills. This is because profit vs cash flow represents two different aspects of a business’s financial health.
Profit shows whether a company earns more than it spends based on accounting principles. Cash flow, however, shows how money actually moves into and out of the business.
Therefore, understanding the difference between profit and cash flow is essential for business owners, managers, and investors.
What Is Profit?
Profit is the amount left after a company subtracts its expenses from its revenue.
For example, if a company generates $500,000 in revenue and records $400,000 in expenses, its accounting profit is $100,000.
However, profit does not necessarily mean that the company has $100,000 available in its bank account.
Some revenue may have been recorded before customers actually pay. Similarly, certain expenses may be recognised in the accounts without an immediate cash payment.
As a result, a profitable business can still experience cash shortages.
What Is Cash Flow?
Cash flow refers to the actual movement of money into and out of a business.
Generally, cash flow can be divided into three categories:
- Operating cash flow – cash generated or used by normal business operations.
- Investing cash flow – cash related to investments, property, equipment, and other long-term assets.
- Financing cash flow – cash received from or paid to lenders and shareholders.
Together, these activities show how a business generates and uses cash.
In contrast to accounting profit, cash flow focuses on actual cash movements.
Profit vs Cash Flow: The Key Difference
The main difference between profit and cash flow is timing.
A company may record a sale today but receive the customer’s payment several months later. The transaction can increase reported revenue and profit, while the related cash has not yet entered the bank account.
For this reason, strong sales do not always mean strong cash flow.
Consider a company that sells $200,000 of products on credit. The sale may contribute to revenue and profit, but the company may have to wait 60 or 90 days to receive payment.
Meanwhile, salaries, rent, suppliers, taxes, and other expenses may still need to be paid on time.
Consequently, the company could be profitable while facing short-term cash pressure.
How Can a Profitable Company Run Out of Cash?
Several situations can create this problem.
1. Customers Pay Late
A business may have substantial accounts receivable but insufficient cash in the bank.
For example, a company could report $300,000 in outstanding customer invoices while having only $50,000 available for immediate expenses.
If customers delay payment, the company may struggle to meet its obligations.
2. Rapid Business Growth
Growth can create additional pressure on cash.
When sales increase, a company may need to purchase more inventory, hire employees, expand facilities, or increase marketing spending.
As a result, rapid growth can consume cash even when the business remains profitable.
3. Large Capital Investments
Purchasing equipment, property, vehicles, or technology can require significant cash.
Although these assets may support future growth, the initial cash payment can reduce the company’s available funds.
Therefore, management needs to consider both profitability and liquidity before making major investments.
4. Debt Repayments
Loan repayments can also affect cash flow.
Interest expense may affect profit, while repayment of the principal generally affects cash without being recorded as an expense in the same way.
This distinction makes cash-flow planning particularly important for businesses with significant debt.
Why Cash Flow Matters
Cash is required to keep a business operating.
Employees need to be paid. Suppliers expect payment. Rent, taxes, loan obligations, and other expenses must also be settled.
Even when the income statement shows a profit, insufficient cash can create serious operational problems.
That is why business owners should monitor cash flow regularly rather than relying solely on the profit and loss statement.
How to Improve Cash Flow
Businesses can take several practical steps to improve their cash position.
Improve Receivables Collection
Set clear payment terms and follow up on overdue invoices promptly.
In addition, businesses can review customer credit policies to reduce the risk of significant payment delays.
Manage Inventory Carefully
Excess inventory can tie up valuable cash.
By monitoring inventory levels and purchasing patterns, businesses can reduce unnecessary cash being locked into stock.
Control Operating Expenses
Regularly reviewing expenses can help management identify unnecessary or inefficient spending.
At the same time, cost control should not undermine essential business activities or long-term growth.
Prepare Cash Flow Forecasts
A cash flow forecast helps management estimate future cash inflows and outflows.
Moreover, it can highlight potential cash shortages before they become urgent problems.
Negotiate Supplier Terms
Where appropriate, businesses may negotiate payment terms with suppliers.
For instance, longer payment periods can provide additional flexibility when cash inflows and outflows do not occur at the same time.
Profit vs Cash Flow: Which Is More Important?
There is no simple answer.
Profit is important because it indicates whether the business model can generate earnings.
Cash flow is equally important because the company needs sufficient liquidity to meet its financial obligations.
Ultimately, a healthy business needs both sustainable profitability and effective cash-flow management.
A company that consistently loses money cannot remain sustainable indefinitely. On the other hand, a profitable company with poor cash management can also face serious financial difficulties.
How an Audit Can Help
An independent audit does not solve cash-flow problems by itself. Nevertheless, the audit process can provide useful insight into financial reporting and areas that may require management attention.
For example, auditors may examine areas such as revenue recognition, receivables, inventory, liabilities, and financial statement presentation.
Furthermore, reviewing financial information can help management better understand the relationship between reported profit and the company’s financial position.
For businesses that want to strengthen their financial reporting and understand potential risks, working with a professional audit firm in Singapore can provide an independent perspective.
Profit vs Cash Flow: A Simple Example
Imagine Company A reports:
- Revenue: $1,000,000
- Expenses: $800,000
- Accounting profit: $200,000
At first glance, the company appears financially successful.
However, suppose $300,000 of the revenue has not yet been collected from customers.
The company may therefore have a $200,000 accounting profit while experiencing much tighter cash availability.
In other words, profit does not automatically equal cash in the bank.
This simple example demonstrates why business owners should review both financial performance and cash movements.
Why Business Owners Should Monitor Both
Profit helps answer the question:
“Is the business making money?”
Cash flow answers another critical question:
“Does the business have enough cash to meet its obligations?”
Together, these measures provide a more complete picture of financial health.
Reviewing both regularly can help management identify potential problems earlier and make better-informed financial decisions.
Final Thoughts
Understanding profit vs cash flow is essential for effective financial management.
A profitable company can still experience financial pressure if customers pay slowly, inventory grows too quickly, debt repayments increase, or major investments consume available cash.
Therefore, business owners should look beyond the profit figure and monitor cash flow carefully.
In addition, accurate financial reporting and regular financial review can help management understand where money is being generated, where it is being spent, and where potential risks may exist.
Ultimately, profit measures performance, while cash flow helps determine whether a business has the liquidity to keep operating.
A successful business needs both.
Profit creates value. Cash flow keeps the business moving.
References / Sources
- IFRS Foundation – IAS 7: Statement of Cash Flows
Provides guidance on cash-flow reporting and the classification of cash flows into operating, investing and financing activities. - Accounting and Corporate Regulatory Authority (ACRA) – Financial Statements
Provides information on financial statement requirements for Singapore companies. - ACRA – Corporate Compliance and Financial Profile
Provides information about financial indicators including profitability, liquidity, operating efficiency and solvency. - IRAS – Record Keeping Requirements
Provides guidance on Singapore businesses’ requirements for maintaining accounting and supporting records.
 English
 Chinese