Vietnam Accounting Closing Process: Year-End Guide
A structured Vietnam accounting closing process helps businesses organize financial records before they finalize year-end reporting. During the closing period, accounting teams review transactions, reconcile balances, record necessary adjustments, and prepare financial information for management review.
For foreign-owned companies and growing businesses, year-end accounting can require additional coordination. Local accounting requirements may need to work alongside group reporting, internal controls, tax procedures, and audit preparation. Therefore, businesses can benefit from a clear and repeatable closing process.
This guide explains the Vietnam year-end accounting process step by step. It also provides a practical checklist that businesses can use to organize their year-end accounting activities.
Why the Vietnam Accounting Closing Process Matters
The Vietnam accounting closing process gives businesses an opportunity to review their financial records before they finalize the reporting period.
For example, an accounting team may identify:
- Unrecorded expenses
- Outstanding customer balances
- Supplier balances that require reconciliation
- Missing supporting documents
- Incorrect account classifications
- Unupdated fixed asset records
- Unreconciled bank transactions
- Foreign exchange differences
- Incorrect accruals or prepayments
In addition, businesses can address these issues before they finalize financial statements. As a result, the company can improve the reliability of its financial information.
Moreover, a consistent year-end accounting process in Vietnam can help management understand financial performance more clearly.
Therefore, businesses can also use the closing process to identify recurring accounting issues. Over time, this approach can support stronger accounting controls throughout the following year.
At the same time, the process can help accounting teams identify areas that require additional review.
For businesses looking for ongoing accounting support, the USafe Vietnam Services page provides an overview of available professional services.
Vietnam Year-End Accounting Process: Step-by-Step
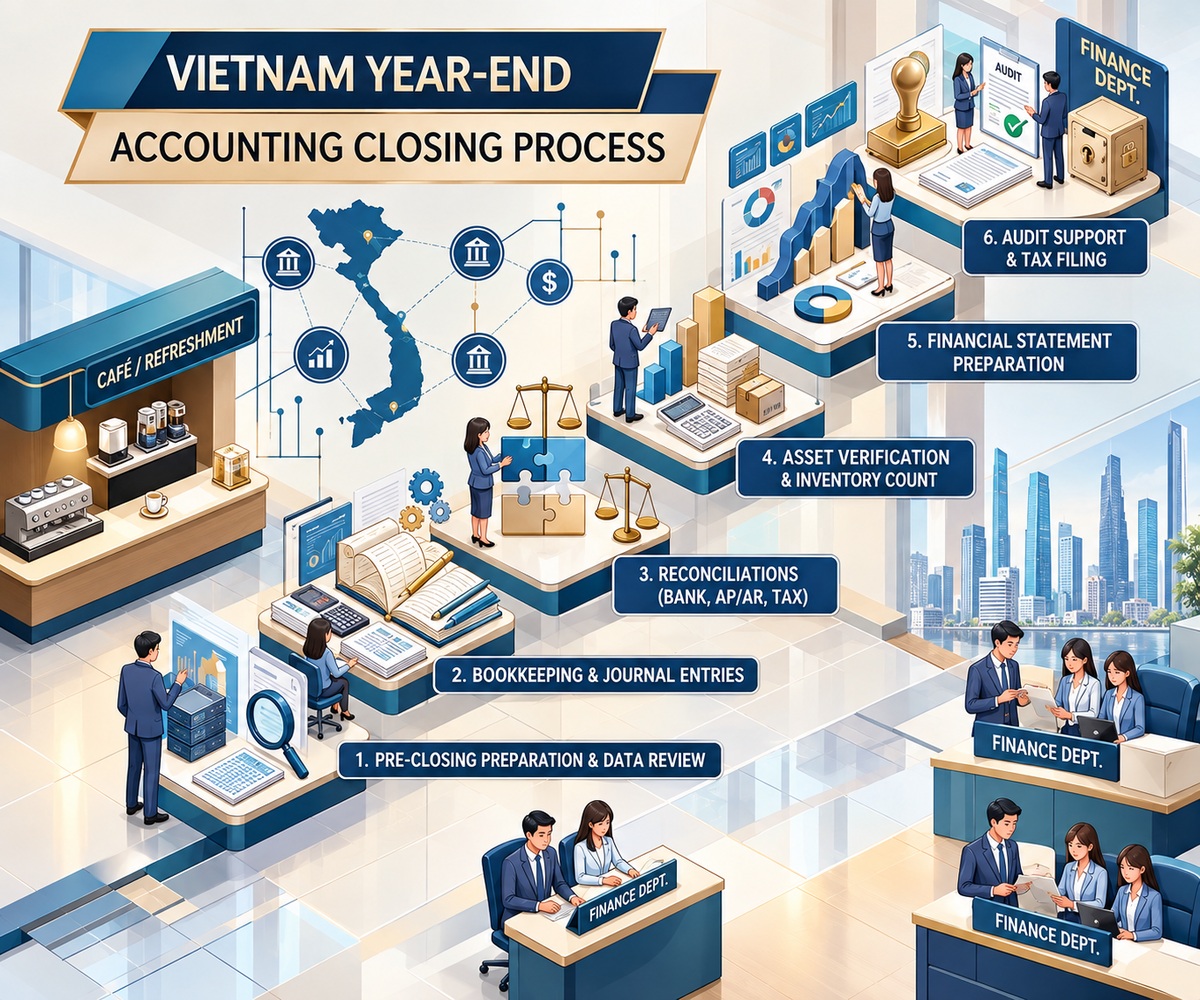
A practical Vietnam year-end accounting process should follow a consistent sequence.
First, the accounting team should confirm that the underlying transaction records are complete. Next, the team can reconcile important accounts and investigate unusual balances. Then, the company can record appropriate adjustments before preparing its final financial information.
After that, the accounting team can review the resulting balances and prepare the financial statements.
As a result, a structured process can make year-end accounting easier to manage.
1. Complete Transaction Recording
First, the accounting team should confirm that the company has recorded the relevant transactions for the reporting period.
The accounting team should review:
- Sales
- Purchases
- Operating expenses
- Payroll
- Bank transactions
- Asset purchases
- Loans and financing
- Intercompany transactions
Furthermore, the team should investigate unusual or incomplete transactions before starting the final reconciliation.
In addition, the team should check whether significant transactions have appropriate supporting documents.
For this reason, a reliable accounting closing process in Vietnam begins with complete and properly supported transaction records.
2. Complete Bank Reconciliation
Next, the accounting team should complete bank reconciliations.
The team can compare accounting records with bank statements and investigate differences.
Common reconciliation items include:
- Outstanding payments
- Deposits in transit
- Bank charges
- Interest income or expenses
- Foreign currency movements
- Bank transactions that have not yet entered the accounting system
For example, a timing difference may occur when a company records a payment before the bank processes it.
Consequently, the accounting team should investigate unexplained differences before finalizing the accounting period.
In addition, regular bank reconciliation can help prevent similar differences from accumulating during the year.
3. Review Accounts Receivable
After completing bank reconciliations, businesses should review accounts receivable.
The review can cover:
- Customer aging reports
- Long-outstanding invoices
- Credit notes
- Customer advances
- Unusual movements
- Potentially uncollectible balances
Moreover, aged receivables can provide useful information about the company’s cash-flow position.
For this reason, the accounting team should investigate significant balances rather than automatically carrying them into the next reporting period.
As a result, businesses can maintain more reliable receivable information.
Furthermore, regular receivable reviews can help management identify collection issues earlier.
4. Review Accounts Payable
Similarly, the accounting team should review accounts payable before closing the period.
The review can include:
- Outstanding supplier invoices
- Unrecorded liabilities
- Supplier advances
- Credit notes
- Long-outstanding balances
- Significant transactions recorded near year-end
In particular, the team should check whether the company has received goods or services that it has not yet recorded as expenses or liabilities.
Therefore, reviewing supplier balances can help businesses reduce unexplained balances at year-end.
In addition, the accounting team should investigate significant differences before it closes the accounts.
Meanwhile, businesses can continue collecting missing supplier documentation where necessary.
5. Check Inventory Records
For businesses that hold inventory, inventory review represents another important part of the Vietnam year-end accounting process.
First, companies should review:
- Inventory quantities
- Inventory valuation
- Slow-moving items
- Damaged goods
- Obsolete inventory
- Goods received but not yet invoiced
- Goods sold but not yet delivered
In addition, businesses should maintain appropriate inventory records and supporting documentation.
For example, the accounting team may need to investigate differences between physical quantities and accounting records.
Consequently, accurate inventory information can help the company present a more reliable financial position.
Furthermore, regular inventory reviews can help businesses identify damaged or obsolete items earlier.
6. Review Fixed Assets
The next step involves reviewing the fixed asset register.
The accounting team should check:
- Newly acquired assets
- Assets disposed of during the year
- Assets transferred between locations
- Depreciation
- Assets no longer in use
- Construction or projects in progress
Furthermore, the team should compare accounting records with supporting documents and the company’s actual asset information.
For this reason, businesses can identify missing asset records, incorrect depreciation entries, or assets that require further investigation.
In addition, regular asset reviews can make year-end reconciliation more efficient.
7. Review Accruals and Prepayments
Some expenses relate to the current accounting period even when the company has not yet received an invoice or made payment.
Therefore, businesses should review potential accruals before finalizing the accounts.
Common examples include:
- Professional services
- Utilities
- Employee-related expenses
- Interest
- Rent
- Bonuses
- Other services received before year-end
At the same time, the accounting team should review prepaid expenses and determine which amounts relate to future periods.
As a result, a careful review can help businesses assign expenses to the appropriate reporting period.
Moreover, this review can improve the consistency of financial reporting from one period to another.
8. Review Foreign Currency Balances
Foreign currency transactions can create additional accounting considerations for businesses that operate internationally.
For example, companies may hold foreign currency bank accounts, receivables, payables, loans, or intercompany balances.
Therefore, the accounting team should review these accounts during the Vietnam accounting closing process.
In particular, the team should identify relevant foreign exchange differences and apply the accounting treatment required by the applicable framework.
Moreover, this step matters especially for foreign-owned companies and businesses that work with overseas customers, suppliers, or related entities.
9. Reconcile Tax-Related Accounts
Another important step involves reviewing tax-related balances.
Depending on the company’s activities, the review may cover:
- Value-added tax
- Corporate income tax
- Personal income tax
- Other applicable taxes and statutory obligations
Next, the accounting team should compare relevant accounting balances with tax records and filings.
If the team identifies differences, it should investigate the underlying reasons and maintain appropriate supporting documentation.
In addition, businesses should keep their accounting and tax records organized so they can respond efficiently to future reviews.
Consequently, regular tax reconciliation can make year-end reporting more organized.
10. Review Intercompany Transactions
Companies that belong to regional or international groups may record transactions with related entities.
For example, these transactions can include:
- Management fees
- Service charges
- Intercompany loans
- Purchases and sales
- Reimbursements
- Shared costs
Next, the accounting team should reconcile intercompany balances with the corresponding records of related entities.
As a result, regular reconciliation can reduce differences between group entities during consolidated reporting.
Furthermore, this step becomes particularly important when the business manages multiple currencies or cross-border services.
11. Review the General Ledger
Finally, the accounting team should review the general ledger after completing the major reconciliations.
The team can investigate:
- Unusual account movements
- Unexpected expenses
- Large journal entries
- Negative balances
- Significant fluctuations
- Transactions posted to unusual accounts
Furthermore, comparing current-year results with prior periods can help identify unexpected movements.
However, the goal is not to eliminate every difference.
Instead, the company should understand significant changes and maintain appropriate explanations or supporting evidence.
Overall, this final review can help management understand whether the accounting records accurately reflect the business.
Financial Reporting After the Accounting Closing Process
Once the main closing procedures are complete, the company can prepare its financial statements.
Financial reporting commonly covers information about:
- Assets
- Liabilities
- Equity
- Revenue
- Expenses
- Profit or loss
- Cash flows
However, the applicable reporting requirements depend on the company’s circumstances and accounting framework.
Before finalizing the reports, the accounting team should review significant balances and confirm that the financial information remains internally consistent.
In addition, management can review important changes compared with previous reporting periods.
Therefore, financial statement review should form an important part of the year-end closing process.
Finally, the company can complete the relevant reporting procedures once the accounting team resolves significant outstanding issues.
For broader accounting support, businesses can also review uSafe Accounting and Bookkeeping Services.
Vietnam Accounting Closing Checklist
A practical Vietnam accounting checklist can help accounting teams manage year-end activities consistently.
| Closing area | Key review point |
|---|---|
| Transactions | Confirm significant transactions are recorded |
| Bank | Complete bank reconciliations |
| Receivables | Review aging and outstanding balances |
| Payables | Check supplier balances and unrecorded liabilities |
| Inventory | Reconcile quantities and valuation |
| Fixed assets | Update additions, disposals, and depreciation |
| Accruals | Review expenses relating to the reporting period |
| Prepayments | Identify expenses relating to future periods |
| Foreign currency | Review relevant foreign currency balances |
| Tax | Reconcile accounting and tax-related records |
| Intercompany | Reconcile related-party balances |
| General ledger | Investigate unusual movements |
| Financial statements | Review reports before finalization |
| Audit | Organize supporting documentation |
By using the same checklist throughout the year, businesses can make the Vietnam year-end accounting process more consistent.
In addition, a standardized checklist can help different members of the accounting team follow the same procedures.
Common Vietnam Year-End Accounting Mistakes
Several issues can make the closing process more difficult.
Fortunately, businesses can reduce many of these problems through regular reviews.
Starting the Closing Process Too Late
Waiting until the final reporting period to identify accounting issues can create unnecessary pressure.
Instead, businesses should reconcile important accounts regularly throughout the year.
As a result, the accounting team has more time to investigate unusual balances and collect missing documents.
Ignoring Old Account Balances
Long-outstanding receivables, payables, advances, and other balances can create questions during year-end review.
Therefore, businesses should review significant old balances instead of carrying them forward automatically.
In addition, each material balance should have a clear explanation and appropriate supporting information.
Maintaining Incomplete Documentation
Accounting records need appropriate supporting documents.
For example, missing contracts, invoices, receipts, bank records, or other evidence can make transaction reviews more difficult.
Consequently, businesses should organize financial documentation throughout the year rather than waiting until year-end.
Failing to Reconcile Intercompany Balances
Small differences between related entities can become harder to resolve when businesses leave them until the final reporting stage.
For this reason, regular intercompany reconciliation can help companies identify differences earlier.
Moreover, early reconciliation gives related entities more time to investigate and resolve discrepancies.
Treating Closing as Only an Administrative Task
Year-end accounting involves more than entering the final transactions of the year.
Instead, the closing process gives management an opportunity to review financial information and identify potential weaknesses in accounting procedures.
Furthermore, this review can help businesses improve their accounting controls for future reporting periods.
How to Improve the Vietnam Accounting Closing Process
Businesses can improve their closing procedures by creating a consistent monthly and year-end routine.
Use a Closing Calendar
First, assign deadlines to each accounting activity.
Then, identify the responsible team member for each task.
As a result, a clear calendar can make responsibilities easier to track.
Reconcile Accounts Regularly
Next, reconcile important balances throughout the year instead of waiting until year-end.
Moreover, regular reconciliation can make the final Vietnam accounting closing process faster and more manageable.
Maintain Organized Documentation
In addition, businesses should store supporting documents in a structured and accessible system.
Consequently, an organized document system can reduce the time required to locate evidence during financial reviews or
Sources
- Vietnam Ministry of Finance – Legal Documents Database— Accounting and financial reporting regulations.
- Vietnam General Department of Taxation — Tax administration, invoices and tax-related regulations.
- uSafe Vietnam Services — Accounting, bookkeeping, reporting compliance and audit services.
 English
 Chinese