Why Your Business Cash Flow Looks Healthy but Your Bank Balance Doesn’t
Your business may show healthy sales and positive cash flow, yet your bank balance can still feel surprisingly low. This situation is common for growing businesses, especially when payments, expenses, taxes, and customer collections happen at different times.
Understanding the difference between cash flow vs bank balance can help business owners identify where their money is going and make better financial decisions.
Cash Flow vs Bank Balance: What Is the Difference?
Cash flow and bank balance are related, but they do not mean the same thing.
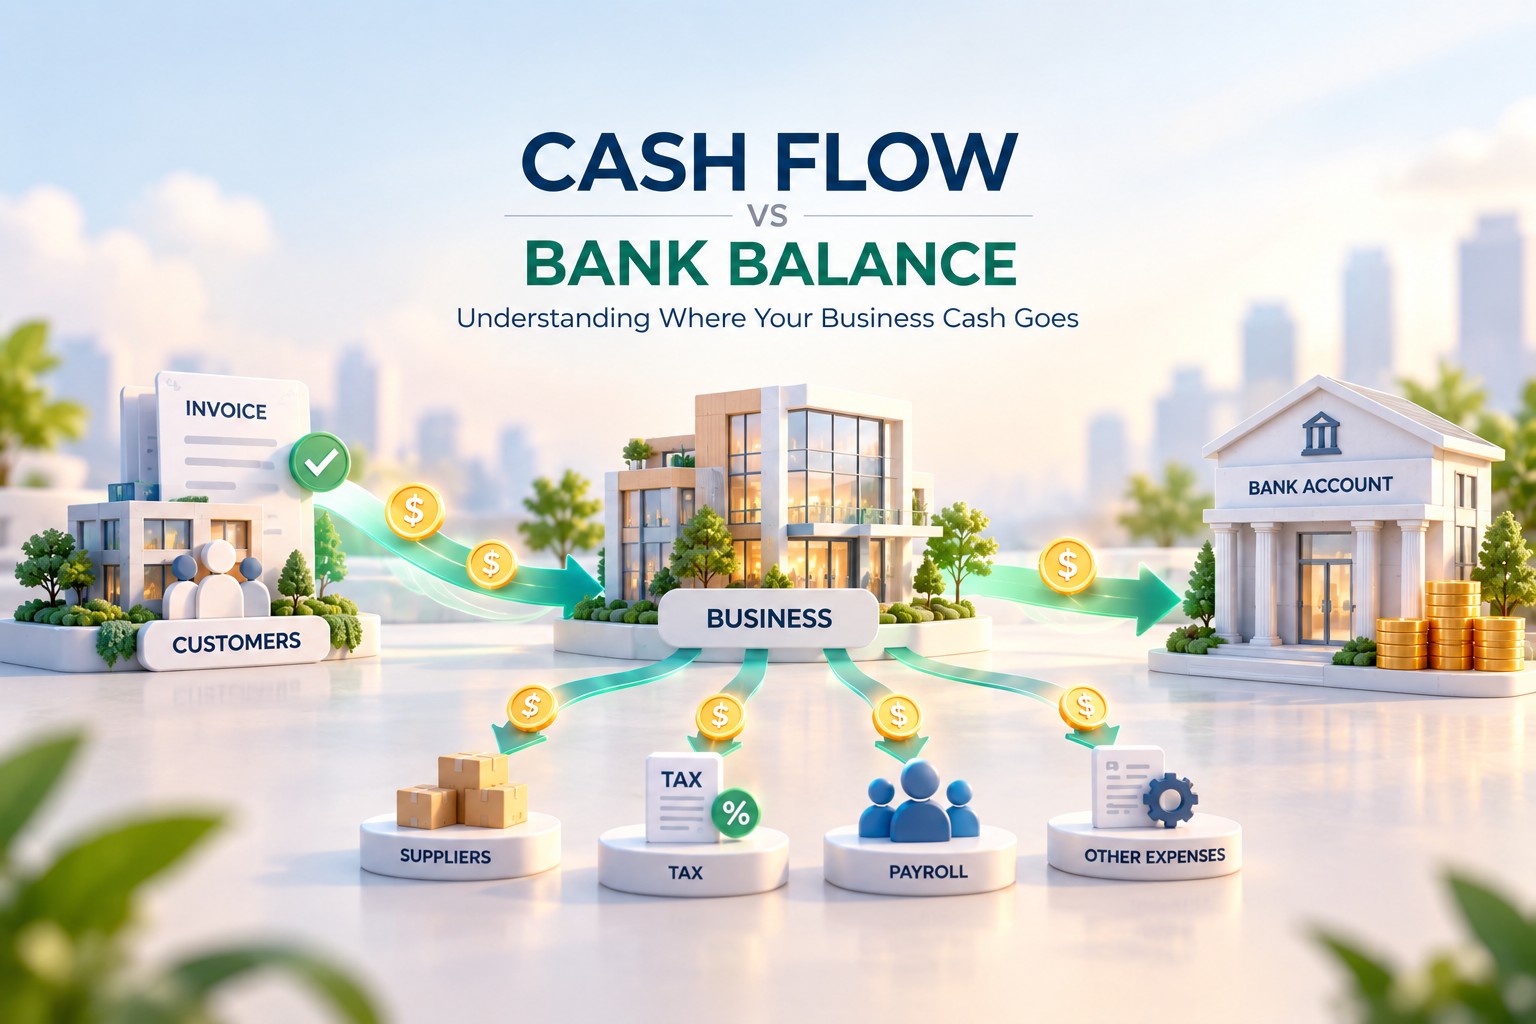
Your bank balance shows how much money is available in your bank account at a specific point in time. In contrast, cash flow looks at how money moves into and out of the business over a period.
For example, a company may issue several large invoices in September. Those invoices increase expected cash inflows, but customers may not pay until October or November.
As a result, the business can have strong sales while still having limited cash available today.
A Simple Example
Imagine your company has:
- $100,000 in sales
- $70,000 in expenses
- $30,000 in expected profit
At first glance, the financial results look positive.
However, if $60,000 of your invoices have not been collected yet, your bank account may still have much less cash than expected.
This is why looking only at revenue or profit can give business owners an incomplete picture.
1. Your Customers Have Not Paid Their Invoices Yet
One of the most common reasons for a low bank balance is slow customer collection.
Your accounting records may show revenue when an invoice is issued or when the relevant accounting requirements are met. However, the money may not arrive in your bank account immediately.
This creates a timing difference between recorded business activity and actual cash received.
What Should You Check?
Review:
- Outstanding invoices
- Overdue customer balances
- Payment terms
- Average collection time
- Large customers with delayed payments
A business with increasing accounts receivable may look successful on paper while experiencing pressure on available cash.
2. Your Business Is Paying Suppliers Before Receiving Customer Payments
The opposite timing problem can happen with suppliers.
Suppose your business must pay suppliers within 30 days, while customers pay within 60 days. Your company may need to pay out cash before receiving the related customer payment.
This gap can create temporary cash pressure.
Therefore, business owners should not only monitor sales. They should also understand the timing of both incoming and outgoing payments.
3. Profit Does Not Equal Available Cash
Profit and cash are different financial concepts.
A company can report a profit while having limited cash because some revenue has not yet been collected. Similarly, certain expenses or payments can reduce cash without appearing as a normal operating expense at the same time.
For this reason, reviewing the income statement alone is not enough.
Business owners should also review:
- Cash flow
- Bank balances
- Accounts receivable
- Accounts payable
- Loans and repayments
- Tax obligations
Together, these figures provide a clearer picture of the company’s financial position.
4. Tax Payments Can Reduce Your Bank Balance Suddenly
Taxes can also create a significant difference between expected and available cash.
A company may set aside cash gradually but make a larger tax payment when the payment becomes due.
If tax obligations are not included in cash planning, the bank balance can fall more quickly than expected.
Build Tax Payments Into Your Cash Planning
Instead of waiting until a tax payment is due, businesses can estimate upcoming obligations and include them in their cash-flow planning.
This makes it easier to understand how much cash is actually available for operations.
5. Loan Repayments Can Affect Cash
Loan repayments are another reason why a business can have positive financial results while seeing its bank balance decrease.
Principal repayments reduce cash, but they are treated differently from interest expenses in financial reporting.
Therefore, business owners should consider financing activities when reviewing their cash position.
6. Your Bank Reconciliation May Not Be Up to Date
Sometimes the problem is not the business’s cash position. The problem is that the accounting records do not match the bank records.
Bank reconciliation helps identify differences between accounting records and actual bank transactions.
Common differences include:
- Bank charges
- Unrecorded payments
- Outstanding transactions
- Customer receipts not yet recorded
- Duplicate entries
- Timing differences
Regular reconciliation helps businesses identify these issues before they become larger problems.
7. Your Business Is Growing Too Quickly
Growth can create cash pressure.
When sales increase, a business may need to:
- Purchase more inventory
- Hire employees
- Pay suppliers
- Increase marketing spending
- Open new locations
- Invest in equipment
These costs can happen before customers pay for the additional sales.
As a result, rapid growth does not always mean immediate improvement in available cash.
Growth Requires Cash Planning
A growing company should monitor expected cash inflows and outflows rather than relying only on historical bank balances.
This helps management identify periods when additional working capital may be required.
8. You Are Looking at the Wrong Financial Numbers
One common mistake is checking only the bank balance.
The bank balance tells you what is available now. It does not tell you what will happen next week or next month.
A more useful monthly review should include:
| Financial Area | What to Check |
|---|---|
| Bank balance | Available cash today |
| Accounts receivable | Money customers owe |
| Accounts payable | Upcoming supplier payments |
| Cash flow | Cash movement over time |
| Taxes | Upcoming tax obligations |
| Loans | Future repayments |
| Expenses | Expected operating costs |
Looking at these numbers together gives business owners a more complete view of their financial position.
How to Improve Your Business Cash Flow
Once the causes are identified, businesses can take practical steps to improve cash management.
Review Outstanding Receivables
Identify overdue invoices and follow up with customers based on clear payment terms.
Monitor Upcoming Payments
Maintain a schedule of supplier payments, payroll, taxes, loan repayments, and other significant expenses.
Reconcile Bank Accounts Regularly
Make sure accounting records are updated and agree with actual bank transactions.
Prepare a Cash Flow Forecast
A cash flow forecast can help estimate expected cash inflows and outflows for the coming weeks or months.
Review Working Capital
Monitor accounts receivable, accounts payable, inventory, and other short-term assets and liabilities.
A Simple Monthly Cash Flow Review
Business owners do not need to wait until year-end to review their cash position.
A practical monthly review can follow five steps:
Step 1: Check Your Actual Bank Balance
Start with the cash currently available in your business bank accounts.
Step 2: Review Money You Expect to Receive
Check outstanding invoices and expected customer payments.
Step 3: Review Upcoming Payments
List major supplier payments, payroll, taxes, loans, and other commitments.
Step 4: Compare Expected Inflows and Outflows
Identify whether the business may experience a cash shortfall during the coming weeks.
Step 5: Investigate Significant Differences
If the expected cash position does not match the actual bank balance, investigate the difference before making major financial decisions.
When Should You Get Professional Accounting Support?
If your business regularly experiences differences between expected cash and available cash, it may be time to review your accounting processes.
Professional accounting support can help businesses improve:
- Bank reconciliation
- Accounts receivable tracking
- Accounts payable management
- Monthly financial reporting
- Cash-flow forecasting
- Financial record accuracy
The goal is not simply to produce financial statements. It is to give management reliable information for everyday decisions.
How uSafe Can Help
uSafe supports businesses with accounting, financial reporting, tax and audit-related services across key Asian markets.
For businesses that need better visibility over their financial information, accurate accounting records and regular reporting can make it easier to understand where cash is coming from, where it is going, and what needs attention.
If your business has healthy sales but your bank balance does not seem to reflect that growth, reviewing your accounting records and cash-flow position can be a useful first step.
Contact uSafe to discuss your accounting and financial reporting needs.
Frequently Asked Questions
Why can a business be profitable but have a low bank balance?
A business can be profitable while having limited cash because revenue may not have been collected yet. Other factors, such as supplier payments, taxes, loan repayments, and investments, can also reduce available cash.
Is bank balance the same as cash flow?
No. Bank balance represents the cash available in a bank account at a particular time. Cash flow measures money moving into and out of the business over a period.
How often should a business check its cash flow?
Many businesses benefit from reviewing cash flow at least monthly. Businesses with high transaction volumes or tight cash positions may need more frequent monitoring.
What is the best way to identify cash flow problems?
Start by reviewing bank reconciliation, accounts receivable, accounts payable, upcoming expenses, tax obligations, and cash-flow forecasts.
Can accounting records affect cash-flow visibility?
Yes. Delayed or inaccurate accounting records can make it harder to understand actual cash movements and upcoming financial obligations.
Conclusion
A healthy income statement does not always mean a healthy bank balance.
The difference between cash flow vs bank balance often comes down to timing: when customers pay, when suppliers are paid, when taxes are due, and when other financial commitments leave the business.
By regularly reviewing cash flow, receivables, payables, bank reconciliation, and upcoming obligations, business owners can gain a clearer view of their available cash and plan ahead with greater confidence.
 English
 Chinese