Hong Kong Related Party Transactions: An Accounting Guide
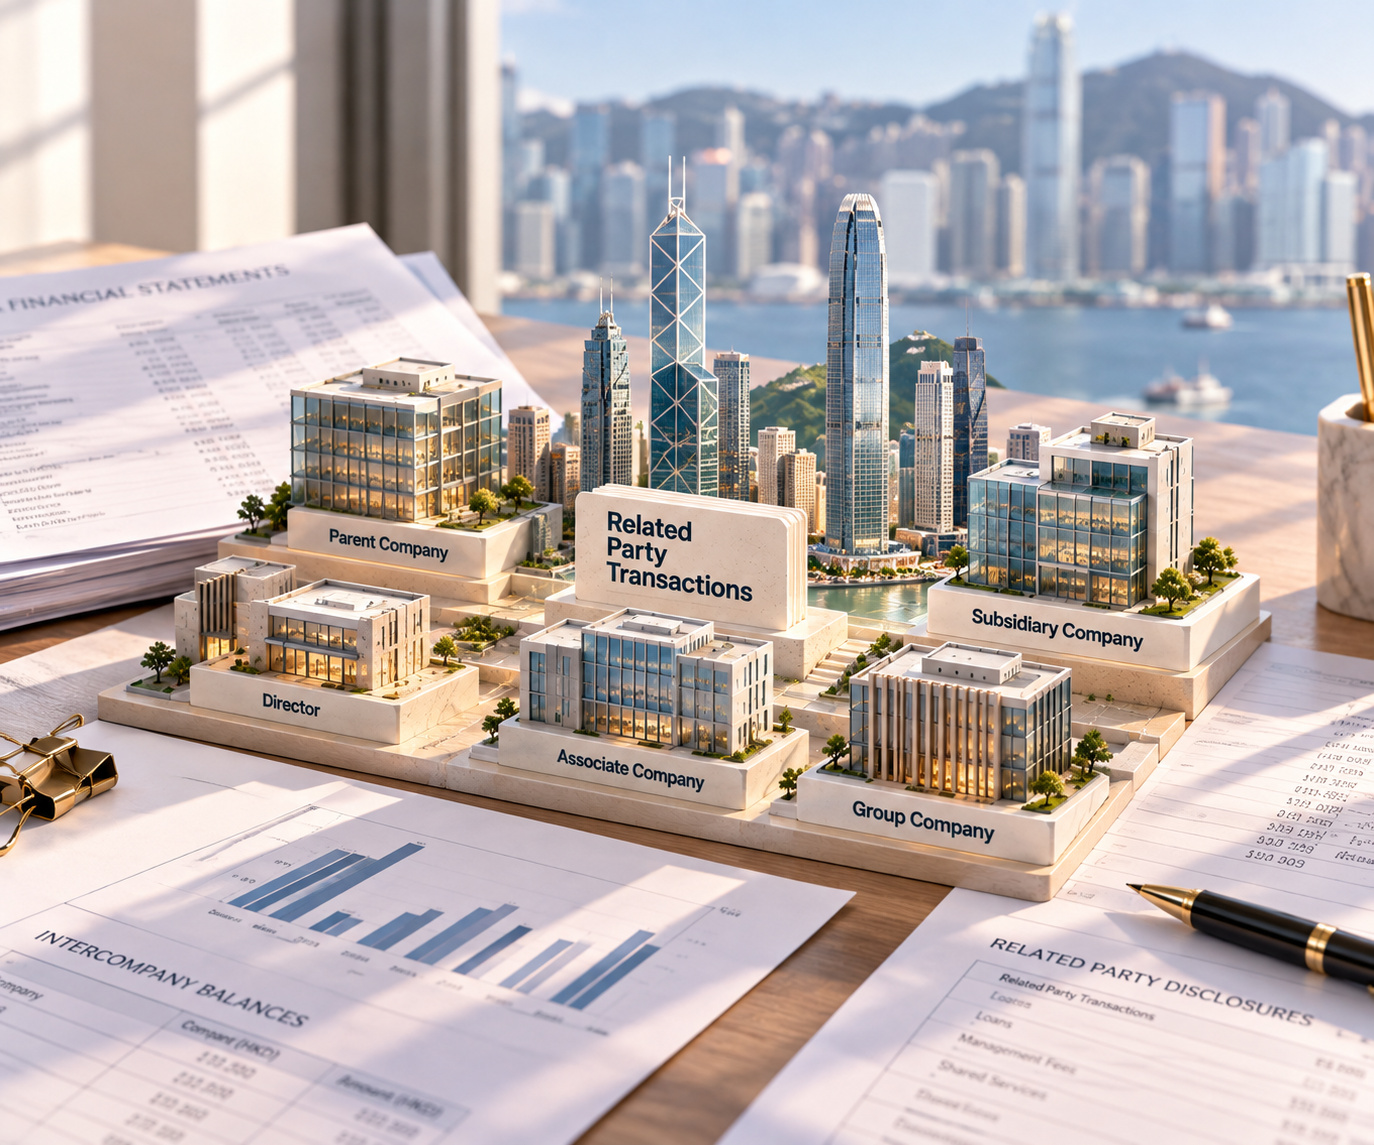
Hong Kong related party transactions require careful accounting because dealings between a company and its directors, shareholders or connected entities can affect financial statements. For example, these arrangements may include director loans, management fees, intercompany balances, shared expenses and transfers of goods or services.
Furthermore, finance teams must do more than record the amounts involved. They need to identify the relationships, verify the underlying transactions and reconcile outstanding balances. In addition, they must determine which disclosures the applicable financial reporting framework requires.
As a result, a structured accounting process helps businesses maintain reliable records, support their statutory audits and explain significant balances clearly.
What Are Hong Kong Related Party Transactions?
Hong Kong related party transactions generally involve transfers of resources, services or obligations between a reporting entity and a related party, whether or not the parties charge a price.
Under Hong Kong Accounting Standard 24 (HKAS 24), businesses assess related party relationships and transactions to determine the disclosures required in their financial statements. The standard also addresses outstanding balances between related parties.
You can consult the official HKAS 24 Related Party Disclosures standard published by the Hong Kong Institute of Certified Public Accountants (HKICPA).
Depending on the circumstances and applicable accounting framework, related parties may include:
- Parent companies and subsidiaries.
- Entities under common control.
- Associates and joint ventures.
- Directors and other key management personnel.
- Certain close family members of key management personnel.
- Entities that relevant individuals control or significantly influence.
However, businesses should assess each relationship against the standard’s actual definitions rather than assume that every shareholder, supplier or family member automatically qualifies as a related party.
Why Related Party Accounting Matters During an Audit
Related party dealings are common in corporate groups. However, companies still need to document these transactions carefully because their terms may differ from those used with independent parties.
For instance, a subsidiary may receive funding from its parent company without an immediate repayment date. Similarly, a director may pay business expenses personally and request reimbursement later.
Without proper documentation, finance teams may overlook balances or classify transactions incorrectly. Therefore, businesses should maintain clear records, reconcile outstanding amounts and review the required disclosures before finalising their financial statements.
A consistent process helps businesses:
- Identify transactions that require specific accounting treatment.
- Reconcile balances between related entities.
- Distinguish business expenses from personal or non-business amounts.
- Support the classification of loans, payables and receivables.
- Prepare relevant financial statement disclosures.
- Identify transactions that may require additional corporate approval or legal review.
Five Related Party Accounting Areas Finance Teams Should Review
1. Director Loan Accounts
Director loan accounts can become difficult to reconcile when directors pay company expenses personally, withdraw funds, receive advances or repay amounts at irregular intervals.
For example, when a director pays a supplier using personal funds, the company may record an amount payable to the director if the expense qualifies as a business expense and the company holds appropriate supporting evidence.
By contrast, a transfer from the company to a director may represent a loan, reimbursement, remuneration or another type of transaction. Finance teams should determine the correct classification from the facts, agreements and supporting documents.
To maintain accurate records, finance teams should review:
- Opening and closing director loan balances.
- Transfers between company and director bank accounts.
- Expense reimbursements and supporting receipts.
- Repayments and interest, where applicable.
- Written loan terms and repayment arrangements.
- Balance sheet classification and applicable disclosures.
Furthermore, an unexplained director balance may prompt the auditor to ask for additional evidence about its purpose, classification, approval and recoverability.
Companies should also consider the legal requirements that apply to director loans. The Hong Kong Companies Ordinance contains restrictions and approval provisions for certain loans and similar transactions involving directors and connected persons. The applicable rules depend on the transaction, company type and any relevant statutory exception.
For official guidance, see the Hong Kong Companies Registry’s explanation of provisions affecting directors.
2. Intercompany Loans and Outstanding Balances
Businesses with group structures often transfer funds between parent companies, subsidiaries and fellow subsidiaries. These transfers may support working capital, centralised treasury arrangements or shared operational costs.
Nevertheless, each entity must record the underlying arrangement accurately. For example, one company may record a transfer as a loan while the receiving company records it as income or fails to record it altogether.
To prevent these differences, finance teams should maintain an intercompany reconciliation schedule that identifies:
- The lending and borrowing entities.
- The principal amount and transaction date.
- The purpose and terms of the arrangement.
- Interest calculations, where applicable.
- Repayments and outstanding balances.
- Differences between the entities’ accounting records.
At year-end, finance teams should confirm material balances with the relevant group entities and investigate discrepancies.
When businesses prepare consolidated financial statements, they generally eliminate qualifying intragroup balances and transactions during consolidation under the applicable accounting standards. However, each entity must still maintain accurate individual records and assess its own reporting obligations.
3. Management Fees and Shared Expenses
A parent company may provide finance, human resources, administration, IT or management services to its subsidiaries. The group may then allocate costs or charge management fees between entities.
These arrangements need sufficient documentation to explain the services provided, the calculation method and the entity that benefited from the expenditure.
Finance teams should retain service agreements, invoices, allocation schedules and supporting calculations. In addition, they should check that each entity records the charges in the appropriate accounting period.
For audit purposes, the team should be able to explain how it calculated each material charge and which documents support the amount.
Furthermore, related party pricing may raise separate tax and transfer pricing questions. Businesses should assess these requirements independently because accounting disclosures and tax compliance serve different purposes.
4. Related Party Sales and Purchases
Companies may sell products or provide services to other entities within the same group. Finance teams must apply the relevant revenue recognition and expense recognition requirements to these transactions.
To support accurate reporting, they should compare invoices, delivery records, service evidence and intercompany balances.
They should also investigate differences in transaction dates, foreign currency conversions, credit notes and settlement amounts.
Although the parties belong to the same group, they still need reliable transaction records. In addition, finance teams should assess related party pricing and any relevant tax obligations separately from the accounting treatment.
5. Guarantees and Other Financial Commitments
Related party arrangements may include guarantees, security arrangements and other commitments that do not involve an immediate cash transfer.
Even when no payment occurs before year-end, these arrangements may affect financial reporting. Therefore, finance teams should identify guarantees provided or received, review contractual terms and assess whether the applicable accounting framework requires recognition or disclosure.
Where a director or connected entity participates in the arrangement, the company should also consider any relevant legal, governance and approval requirements.
How to Reconcile Related Party Balances Before Year-End
A consistent reconciliation process helps finance teams identify missing transactions and resolve differences before they finalise financial statements.
Step 1: Maintain a Related Party Register
Create a register of relevant entities and individuals based on the applicable accounting definition. Then, update the register whenever ownership, control or management relationships change.
Finance teams should review the register periodically and use it to identify transactions that may require additional scrutiny.
Step 2: Extract Transactions from the General Ledger
Identify accounts for director loans, intercompany receivables, intercompany payables, management fees, related party sales and other relevant balances.
Where practical, use consistent account codes or transaction tags. This approach makes it easier to identify related party items and prepare supporting schedules.
Step 3: Match Balances Between Counterparties
Compare the amounts recorded by both parties. Check transaction dates, currencies, exchange rates, invoices, credit notes and payments.
If differences arise, record the cause, assign responsibility and establish a target date for resolution. Furthermore, escalate material discrepancies that remain unresolved.
Step 4: Verify Supporting Documents
Review loan agreements, service agreements, invoices, bank statements, payment evidence and relevant approvals.
If documents are missing, determine whether the company can obtain additional evidence. Meanwhile, assess whether the existing evidence supports the transaction’s accounting treatment.
Step 5: Assess Classification and Disclosure
Determine whether each material balance represents a receivable, payable, loan or another category. Next, consider the required related party disclosures and any separate statutory approval or tax assessment.
Finance teams should document the reasons for significant classification decisions and explain any material adjustments.
Step 6: Document the Final Review
Keep the reconciliation schedule, supporting documents, proposed adjustments and review approval together. Consequently, the company can explain how it determined the final balance and resolved any differences.
What Should Companies Disclose About Related Parties?
HKAS 24 sets out disclosure requirements for related party relationships, transactions and outstanding balances. The exact disclosures depend on the nature of the relationship, the transactions and the applicable reporting framework.
Where relevant, financial statement notes may include:
- The nature of the related party relationship.
- Transaction amounts during the reporting period.
- Outstanding balances and relevant commitments.
- Terms and conditions, including security and settlement arrangements.
- Guarantees given or received.
- Provisions for doubtful debts relating to outstanding related party balances.
- Key management personnel compensation, as required by the standard.
Businesses should assess each disclosure requirement rather than assume that every transaction requires identical information.
Furthermore, companies should not automatically describe related party transactions as occurring on arm’s-length terms. They should make such a statement only when they can substantiate it.
The Hong Kong Companies Ordinance may also require specific disclosures concerning directors’ benefits, loans and material interests. Therefore, finance teams should review the relevant statutory provisions alongside the applicable accounting standards.
For additional guidance, consult the Companies Registry’s Accounts and Audit FAQ and the HKICPA’s Companies Ordinance technical resources.
Are Director Loans Permitted in Hong Kong?
Director loans require careful consideration because the Companies Ordinance contains rules governing certain loans, quasi-loans and credit transactions involving directors and connected persons.
However, businesses should not assume that every director loan is automatically prohibited. The relevant restrictions and approval requirements depend on the company, the transaction, the parties involved and any applicable statutory exception.
Before entering into or continuing an arrangement, companies should:
- Identify the parties and the nature of the transaction.
- Review the applicable statutory provisions.
- Determine whether member approval or another exception applies.
- Retain the relevant agreements and approval records.
- Assess the accounting and disclosure requirements separately.
Importantly, recording a transaction in the accounting system does not establish that the company has satisfied every legal requirement. When the position remains unclear, businesses should seek advice from a qualified Hong Kong legal or accounting professional.
Common Mistakes in Related Party Accounting
Leaving Director Balances Unexplained
A balance carried forward year after year without a clear reconciliation makes it difficult to establish its nature and recoverability.
Practical response: Reconcile the account regularly and document the purpose, supporting evidence and settlement arrangements for material items.
Assuming All Group Transactions Can Be Netted Off
Companies should not automatically offset receivables and payables simply because the entities belong to the same group.
Practical response: Assess presentation and offsetting under the applicable accounting requirements. In addition, maintain separate supporting records for each balance.
Using Inconsistent Intercompany Records
Different transaction dates, exchange rates or account classifications can create differences between entities.
Practical response: Standardise reconciliation templates, reporting deadlines and procedures for resolving discrepancies.
Omitting Relevant Related Party Information
Finance teams may focus on transactions identified through account codes and overlook relationships that the accounting system does not capture.
Practical response: Coordinate with management and company secretarial personnel to identify relevant relationships and update the related party register.
Treating Accounting Disclosure as the Only Requirement
Recording and disclosing a transaction does not necessarily satisfy separate corporate approval, directors’ duties or tax requirements.
Practical response: Assess accounting, legal and tax considerations separately. Then, document the conclusions and retain the supporting evidence.
How uSafe Supports Accounting and Audit Preparation
Related party transactions can create additional work when records remain incomplete, group balances do not agree or the purpose of a director transaction remains unclear.
uSafe provides relevant business support services, including accounting and financial reporting assistance, according to the agreed engagement scope. Depending on the business’s needs, support may include organising accounting records, reconciling balances and preparing supporting schedules for financial reporting and audit preparation.
Businesses should clarify the responsibilities of management, the accounting service provider and the appointed auditor. Management remains responsible for preparing the financial statements, while the independent auditor determines the necessary audit procedures and forms an audit opinion.
Explore the relevant uSafe services:
- Accounting Services: Support bookkeeping, account reconciliation and financial reporting.
- Tax Services: Help organise relevant tax records and reporting information.
- Corporate Secretarial Services: Support applicable corporate records and statutory administration.
With a consistent process for identifying, recording and reviewing related party transactions, businesses can improve the reliability of their financial information and make year-end reporting more manageable.
Frequently Asked Questions
What is a related party transaction in Hong Kong?
A related party transaction generally involves a transfer of resources, services or obligations between a reporting entity and a related party. The applicable accounting framework determines the precise definition and disclosure requirements.
Do Hong Kong companies need to disclose director loans?
Director loans may require specific accounting disclosures and may also fall within provisions of the Companies Ordinance. The exact requirements depend on the transaction, the company’s circumstances and any applicable statutory exception.
How should companies reconcile intercompany loan balances?
Companies should compare the lender’s receivable with the borrower’s payable, verify principal and interest calculations, match repayments and investigate differences before finalising the reporting period.
Are related party transactions prohibited in Hong Kong?
No. Related party transactions are common in corporate groups. However, certain arrangements may require approval or fall within legal restrictions, accounting disclosure requirements or tax rules.
What is HKAS 24?
HKAS 24 is the Hong Kong Accounting Standard that addresses related party disclosures. It explains how reporting entities identify related party relationships and determine the disclosures required in financial statements.
Can companies eliminate related party balances from consolidated financial statements?
Companies generally eliminate qualifying intragroup balances and transactions when preparing consolidated financial statements under the applicable accounting standards. Nevertheless, each entity must maintain accurate individual records and meet its own reporting obligations.
Improve Your Related Party Accounting Process with uSafe
Accurate related party accounting requires more than matching balances. Businesses need to understand the relationships involved, maintain reliable supporting documents, review director and intercompany accounts, and assess the applicable disclosure requirements.
By reviewing transactions regularly and documenting significant balances, finance teams can resolve discrepancies earlier and support more reliable financial statements.
Contact uSafe to discuss accounting, financial reporting and audit support for your Hong Kong business.
 English
 Chinese