Malaysia Audit Readiness 2026: How e-Invoice Is Changing Accounting Controls
Malaysia audit readiness 2026 is becoming increasingly important as businesses manage e-Invoice, accounting data, financial controls, and audit documentation. As digital tax processes become part of everyday operations, companies need more than accurate financial statements at year-end. They also need reliable transaction records, consistent supporting documents, clear approval processes, and effective reconciliation procedures.
For Malaysian businesses, e-Invoice can change how accounting teams capture, validate, store, and reconcile transaction information. Therefore, companies should review their accounting controls throughout the year rather than waiting until the audit begins.
In addition, businesses need a practical process that connects daily transactions with financial reporting. This approach can help finance teams identify errors earlier and prepare supporting information more efficiently.
This guide explains how e-Invoice is changing Malaysia audit preparation and how businesses can strengthen accounting controls throughout 2026.
What Is Malaysia Audit Readiness 2026?
Malaysia audit readiness 2026 refers to a company’s ability to maintain accurate, complete, traceable, and well-supported financial information throughout the financial year.
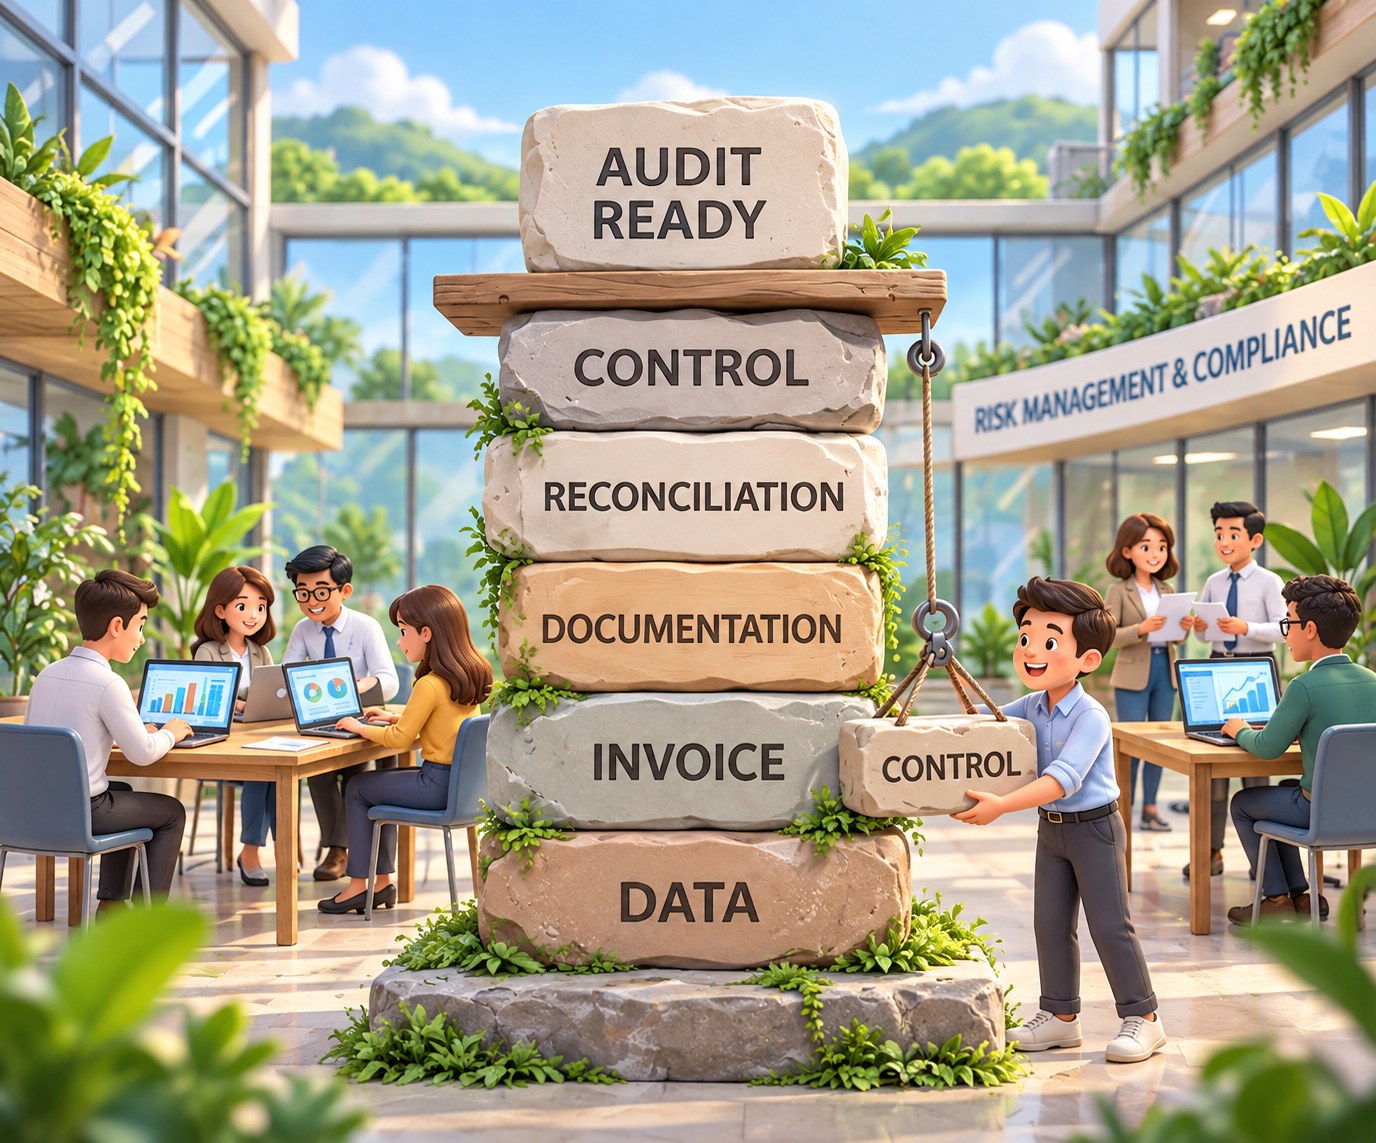
Audit readiness does not simply mean preparing documents when auditors request them. Instead, it means maintaining an accounting environment where finance teams can trace transactions from their original source to accounting records and financial statements.
More importantly, an audit-ready process should help businesses answer several practical questions:
- Where did the transaction originate?
- Who approved the transaction?
- Which document supports the transaction?
- Was the transaction recorded in the correct accounting period?
- Does the accounting entry match the underlying invoice?
- Can the business reconcile the transaction with its bank, customer, supplier, or tax records?
- Can the accounting team retrieve supporting evidence when requested?
In addition, companies should maintain consistent processes across departments. Sales, procurement, finance, tax, operations, and management can all influence the quality of financial information.
Businesses that need support with accounting records, bookkeeping, reconciliations, and financial reporting can explore uSafe’s Accounting, Bookkeeping and Preparing Financial Statements services.
How e-Invoice Is Changing Malaysia Audit Preparation
Malaysia’s e-Invoice framework creates a more structured digital process for transaction information. Consequently, businesses need to consider how invoice information moves between operational systems, accounting systems, and tax processes.
The change matters because inaccurate invoice information can affect several downstream accounting records. Moreover, finance teams need to understand how data moves from the original transaction into the accounting system.
HASiL’s current implementation timeline states that taxpayers with annual turnover or revenue up to RM5 million are scheduled for implementation from 1 January 2026. The same official timeline states that taxpayers with annual turnover or revenue below RM3 million are exempt from e-Invoice implementation. HASiL updated this timeline on 30 August 2026.
However, businesses should not rely on a general threshold alone. They should review the latest HASiL guidance and their own circumstances before determining the applicable implementation position.
HASiL also published e-Invoice Guideline Version 4.8 on 30 August 2026 and Specific Guideline Version 4.9 on 7 September 2026. Therefore, finance teams should use the latest official materials when reviewing their e-Invoice processes.
The official MyInvois documentation explains that the system supports near real-time validation and storage of transactions. As a result, businesses should consider how their accounting systems interact with the e-Invoice process.
For audit preparation, this creates several practical considerations:
| Area | Traditional concern | e-Invoice environment |
|---|---|---|
| Invoice information | Manual document accuracy | Structured digital data |
| Customer details | Manual entry | Greater need for consistent master data |
| Transaction records | Multiple document versions | More structured transaction information |
| Reconciliation | Periodic manual checks | Greater opportunity for system-based matching |
| Audit trail | Supporting documents | Digital records plus accounting evidence |
| Error management | Manual correction | Defined validation and correction processes |
As a result, businesses should treat e-Invoice as part of their wider accounting control environment rather than as an isolated tax project.
From One Transaction to Malaysia Financial Audit Readiness
A strong audit trail begins with the transaction itself.
For example, consider a customer sale. The process may involve a quotation, sales order, delivery documentation, invoice information, e-Invoice submission, payment receipt, bank transaction, and accounting entry.
If these records contain inconsistent information, the accounting team may need additional time to explain the differences during an audit.
Therefore, businesses should create a clear transaction flow:
Customer transaction → Invoice data → e-Invoice process → Accounting entry → Payment → Bank reconciliation → Financial reporting
Each stage should connect logically with the next one. In addition, businesses should establish clear ownership for each stage.
The finance team may own accounting entries, while sales or operations may maintain customer and transaction information. Without clear responsibilities, however, errors can remain unresolved until year-end.
For this reason, Malaysia financial audit readiness should start with transaction-level controls rather than only financial statement review.
For businesses operating across several Asian markets, uSafe’s Regional Finance Control for Asian Businesses provides additional context on regional reporting, cash flow, intercompany transactions, currencies, and financial controls.
Five Accounting Data Gaps That Affect Audit Readiness in Malaysia
1. Invoice Data and Malaysia Accounting Controls
Incorrect invoice information can create problems beyond the invoice itself.
For example, an incorrect customer name, tax information, transaction amount, or accounting classification can affect several downstream records.
Therefore, businesses should review the information captured at the beginning of the transaction process.
Useful controls include:
- Customer master data checks
- Supplier master data checks
- Invoice numbering controls
- Tax information validation
- Approval procedures
- Accounting code reviews
- Exception reporting
In addition, businesses should define who can create, modify, and approve critical master data.
2. Missing Documents and Malaysia Audit Preparation
Auditors commonly need supporting evidence to understand and verify financial transactions.
Missing documents can make a valid transaction difficult to explain. Therefore, businesses should establish a consistent document-retention process.
Depending on the transaction, supporting evidence may include:
- Contracts
- Purchase orders
- Sales orders
- Delivery records
- Invoices
- e-Invoice records
- Payment evidence
- Bank statements
- Expense claims
- Approval records
- Tax-related documentation
Furthermore, businesses should organize documents so that accounting teams can retrieve them efficiently.
The objective is not simply to store more files. Instead, the objective is to maintain a clear connection between the accounting entry and its supporting evidence.
3. Manual Adjustments and the Audit Trail
Manual journal entries can be necessary. However, frequent or poorly documented adjustments can make financial records harder to review.
Businesses should therefore maintain clear information for material manual adjustments, including:
- Reason for the adjustment
- Person who prepared it
- Person who approved it
- Date of the adjustment
- Accounts affected
- Supporting documentation
A well-managed adjustment process can help the finance team explain unusual movements during an audit.
Moreover, businesses should review recurring manual adjustments. If the same correction appears every month, the underlying process may require improvement.
4. System Reconciliation and Financial Audit Readiness
Reconciliation compares information from different sources and identifies inconsistencies.
For instance, a company may reconcile:
- Bank records against the general ledger
- Accounts receivable against customer balances
- Accounts payable against supplier balances
- Sales records against accounting records
- Inventory records against accounting balances
- Tax records against relevant accounting information
For this reason, monthly reconciliation can help businesses identify problems before year-end.
Furthermore, a reconciliation process should include clear evidence of review. Simply identifying a difference is not enough. The accounting team should document the reason for the difference and the action taken.
5. Customer Data and Accounting Controls in Malaysia
Customer information can influence invoicing, e-Invoice processing, revenue recognition, receivables, and reporting.
If customer information changes without appropriate controls, accounting records can become inconsistent.
Therefore, businesses should establish procedures for:
- Creating new customer records
- Updating customer information
- Reviewing duplicate records
- Validating tax-related information
- Approving changes to master data
- Removing inactive records where appropriate
As a result, good master-data management can reduce errors before they affect financial reporting.
Why Malaysia Audit Preparation 2026 Requires More Than a Year-End Checklist
A year-end checklist can identify missing documents. However, it cannot replace effective controls throughout the year.
When companies wait until the audit starts, they may discover several problems at the same time. These problems can include unreconciled balances, missing supporting documents, unexplained journal entries, inconsistent customer data, or differences between operational and accounting systems.
Consequently, audit preparation should become a recurring finance activity.
A practical monthly cycle can include:
Record → Reconcile → Review → Resolve → Document
As a result, finance teams have more opportunities to correct errors before they accumulate.
In addition, management can use recurring reviews to identify process weaknesses instead of treating each audit issue as an isolated event.
Does Audit Exemption Affect Malaysia Audit Readiness?
Audit exemption does not mean that a company can ignore the quality of its accounting records.
Under section 267 of the Companies Act 2016, private companies generally need to appoint an auditor for each financial year. However, SSM can exempt qualifying private companies subject to the applicable criteria.
For financial periods beginning on or after 1 January 2026, the Phase 2 audit exemption thresholds are RM2 million for annual revenue, RM2 million for total assets, and 20 employees. A company must satisfy at least two of the three criteria, subject to the full requirements of the applicable framework.
Therefore, businesses should distinguish between:
- Whether a company qualifies for an audit exemption; and
- Whether the company maintains reliable financial records.
Even where an audit exemption applies, accurate accounting information remains important for management reporting, taxation, financing, transactions with investors, and other business requirements.
For this reason, companies should not treat audit exemption as a substitute for accounting controls.
Businesses that want a broader overview of Malaysian accounting and audit requirements can also read uSafe’s Malaysia Accounting and Audit Requirements: 2026 Guide.
A Practical Malaysia Audit Readiness 2026 Framework
Businesses can use the following framework to review their accounting environment.
1. Transaction Accuracy and Accounting Controls
Start with the source transaction.
First, confirm that the transaction contains accurate information before it reaches the accounting system.
Review:
- Transaction dates
- Customer or supplier information
- Amounts
- Tax information
- Account classifications
- Supporting documents
- Approval status
As a result, this step creates the foundation for Malaysia audit readiness 2026.
2. e-Invoice and Malaysia Audit Preparation
Businesses should understand how e-Invoice information interacts with their existing accounting workflow.
For example, review whether:
- Invoice information flows consistently between systems
- Errors have a defined correction process
- Staff understand their responsibilities
- Customer and supplier information remains accurate
- e-Invoice records can be retrieved when required
- Accounting records remain consistent with transaction documentation
Furthermore, companies should monitor official e-Invoice updates because implementation requirements can change.
HASiL’s latest e-Invoice resources should remain the primary reference for implementation timelines, requirements, exemptions, and related arrangements.
3. Reconciliation for Financial Audit Readiness
Reconciliation should happen regularly rather than only at year-end.
A practical schedule may include:
| Reconciliation | Suggested review |
|---|---|
| Bank accounts | Monthly |
| Accounts receivable | Monthly |
| Accounts payable | Monthly |
| Revenue records | Monthly |
| Major balance sheet accounts | Monthly or quarterly |
| Tax-related balances | According to business needs |
However, the exact frequency should depend on transaction volume, risk, business complexity, and management requirements.
4. Documentation for Audit Readiness in Malaysia
Create a clear documentation structure.
For each significant transaction or accounting balance, finance teams should be able to identify the relevant supporting evidence.
In addition, document important accounting judgments, estimates, adjustments, and unusual transactions.
This approach can reduce the time required to reconstruct information during an audit.
5. Approval Controls and Malaysia Accounting Controls
Approval controls help establish accountability.
Businesses should define approval limits based on transaction type and value. They should also separate preparation, review, and approval responsibilities where practical.
For example:
Prepare → Review → Approve → Record → Reconcile
This structure can reduce the risk of errors and improve the audit trail.
6. Audit Trails for Malaysia Financial Reporting
A strong audit trail allows finance teams to understand how a reported figure developed.
For example, a revenue balance should connect to underlying transactions, invoices, customer records, receipts, and accounting entries.
Therefore, companies should consider whether their systems can preserve sufficient information to explain important financial movements.
How to Improve Malaysia Audit Readiness 2026 Before Year-End
Businesses do not need to wait until the financial year closes.
Instead, they can start with a practical review.
Step 1: Identify High-Risk Transactions
Review transactions that involve:
- High values
- Related parties
- Unusual adjustments
- Significant estimates
- Manual processing
- Complex tax treatment
- Multiple systems
These transactions may require stronger documentation and review.
Step 2: Review Reconciliation Status
Prepare a list of unreconciled balances.
Then identify:
- Age of the difference
- Amount involved
- Reason for the difference
- Responsible person
- Corrective action
- Expected resolution date
Consequently, this process gives management better visibility before the audit begins.
Step 3: Review e-Invoice Processes
Check whether the accounting team understands the company’s e-Invoice workflow.
Also, review how the business handles exceptions and corrections.
Moreover, check whether the relevant records remain accessible and consistent with the accounting system.
Step 4: Review Supporting Documents
Select a sample of transactions and trace each one from source documentation to accounting records.
For example:
Contract → Order → Invoice → e-Invoice → Payment → Ledger
If the chain breaks, investigate the reason.
Step 5: Document Control Improvements
Do not simply correct individual errors.
Instead, identify why the error occurred and determine whether the process can prevent it from recurring.
As a result, this approach can improve long-term Malaysia audit preparation.
Building Better Accounting Controls in Malaysia in 2026
Accounting controls should support business operations rather than create unnecessary administrative work.
A practical control environment should be:
- Clear
- Consistent
- Documented
- Proportionate to risk
- Easy to review
- Supported by appropriate technology
Technology can help automate repetitive checks. For example, automated controls can flag missing information, unusual transactions, or mismatched records.
However, automation does not eliminate the need for human review.
The finance team still needs to determine why a mismatch occurred and whether corrective action is necessary.
Therefore, businesses should combine technology with clear responsibilities and documented procedures.
What Malaysian Businesses Should Review for Audit Readiness 2026
A practical review can cover the following areas:
| Area | Key question |
|---|---|
| Revenue | Can the business trace revenue to supporting transactions? |
| Expenses | Can material expenses be supported by appropriate documents? |
| Receivables | Do customer balances reconcile with accounting records? |
| Payables | Do supplier balances match available documentation? |
| Bank | Are bank accounts reconciled regularly? |
| e-Invoice | Does invoice information remain consistent across systems? |
| Journals | Are manual adjustments documented and approved? |
| Master data | Are customer and supplier records controlled? |
| Documents | Can finance teams retrieve supporting evidence efficiently? |
| Audit trail | Can significant balances be traced to underlying transactions? |
Furthermore, businesses should assign responsibility for each area.
A checklist becomes more useful when every action has an owner and a defined review process.
The Role of Accounting Teams in Malaysia Audit Preparation
Accounting teams play an important role in maintaining audit readiness throughout the year.
Their responsibilities may include:
- Maintaining accurate accounting records
- Reviewing transaction documentation
- Performing reconciliations
- Monitoring unusual transactions
- Maintaining audit trails
- Supporting e-Invoice processes
- Documenting adjustments
- Coordinating with auditors
- Escalating unresolved issues
However, audit readiness should not belong only to the accounting department.
Sales, procurement, operations, IT, tax, and management can all influence financial data.
Consequently, businesses should create clear communication between teams.
A Year-Round Approach to Malaysia Financial Audit Readiness
A year-round approach can be divided into four stages.
Monthly
First, focus on transaction accuracy, reconciliations, journal reviews, and unresolved differences.
Quarterly
Next, review accounting controls, master data, unusual transactions, and recurring issues.
Before Year-End
Then, perform a broader review of supporting documents, balances, e-Invoice processes, and outstanding reconciliation items.
Before the Audit
Finally, prepare requested schedules, supporting evidence, explanations, and management responses.
As a result, this structure can make Malaysia audit preparation more manageable because the business addresses issues progressively rather than all at once.
Final Thoughts on Malaysia Audit Readiness 2026
Malaysia audit readiness 2026 is increasingly connected to the quality of accounting data, e-Invoice processes, reconciliation, documentation, and internal controls.
Businesses should therefore look beyond the traditional year-end audit checklist.
Instead, a stronger approach starts with individual transactions and follows the information through invoicing, e-Invoice processes, accounting entries, payments, reconciliation, and financial reporting.
Moreover, regular reviews can help finance teams identify problems earlier.
Ultimately, effective accounting controls can give businesses a clearer financial trail and make audit preparation more organized.
At the same time, companies should review official requirements regularly because tax and corporate compliance frameworks can change.
Frequently Asked Questions About Malaysia Audit Readiness
What is Malaysia audit readiness 2026?
Malaysia audit readiness 2026 is the process of maintaining accurate, complete, traceable, and well-supported financial information throughout the year so the business can respond efficiently to audit requirements.
How does e-Invoice affect audit preparation in Malaysia?
e-Invoice can affect how businesses capture, validate, process, and retain transaction information. Therefore, companies should review their accounting workflows and ensure that transaction data remains consistent across relevant systems.
Does e-Invoice replace accounting controls?
No. e-Invoice is part of the transaction and tax process. However, businesses still need appropriate accounting controls, reconciliations, approvals, documentation, and review procedures.
Does audit exemption mean a company does not need accounting controls?
No. Audit exemption and accounting control are different matters. A company should maintain reliable accounting records regardless of whether it qualifies for an audit exemption.
How often should businesses reconcile their accounts?
Many businesses perform key reconciliations monthly. However, the appropriate frequency depends on transaction volume, business complexity, risk, and management requirements.
What documents should businesses prepare for an audit?
Documents can include contracts, invoices, e-Invoice records, payment evidence, bank records, purchase documentation, sales documentation, journal support, and other records relevant to the financial statements.
How can a company improve Malaysia audit readiness before year-end?
Start by reviewing high-risk transactions, reconciling outstanding balances, checking supporting documents, reviewing e-Invoice workflows, and documenting accounting adjustments.
Why are accounting controls important for audit readiness?
Accounting controls help businesses maintain accurate records, assign responsibilities, reduce errors, and create a clear audit trail. As a result, they can make financial information easier to review and explain.
Strengthen Your Financial Control Process with uSafe
Strong audit readiness starts long before the auditor requests the first document.
If your business needs support with accounting processes, financial controls, compliance coordination, or regional finance operations, uSafe can help you build a more structured approach to financial management.
For accounting records, reconciliations, financial reporting, and bookkeeping support, explore uSafe’s Accounting, Bookkeeping and Preparing Financial Statements services.
For companies managing finance across several Asian markets, Regional Finance Control for Asian Businesses provides a broader perspective on financial coordination and control.
Businesses can also review Malaysia Accounting and Audit Requirements: 2026 Guide for a broader overview of Malaysian accounting and audit considerations.
In addition, businesses that need to review Malaysian corporate tax processes can explore uSafe’s Malaysia Corporate Tax Guide.
The goal is not simply to prepare for one audit.
Instead, the goal is to create accounting processes that remain organized, traceable, and reliable throughout the year.
Contact uSafe to discuss your accounting and financial control needs in Malaysia.
Official Sources
- HASiL – e-Invoice Implementation Timeline
- HASiL – e-Invoice Guidelines
- MyInvois – Getting Started
- SSM – Companies Act 2016
- SSM – Audit Exemption
- SSM – Practice Directive No. 10/2024
 Chinese
 English